Steel price trends in July 2026
time2026/08/15
- July steel PMI rose to 46.1% but stayed sub-50. Aug off-season: weak demand, supply cuts, softening costs. Plate outperforms longs. Early heat/rain curb construction; manufacturing supports flats. Late-month rebound possible as seasonal drag eases.
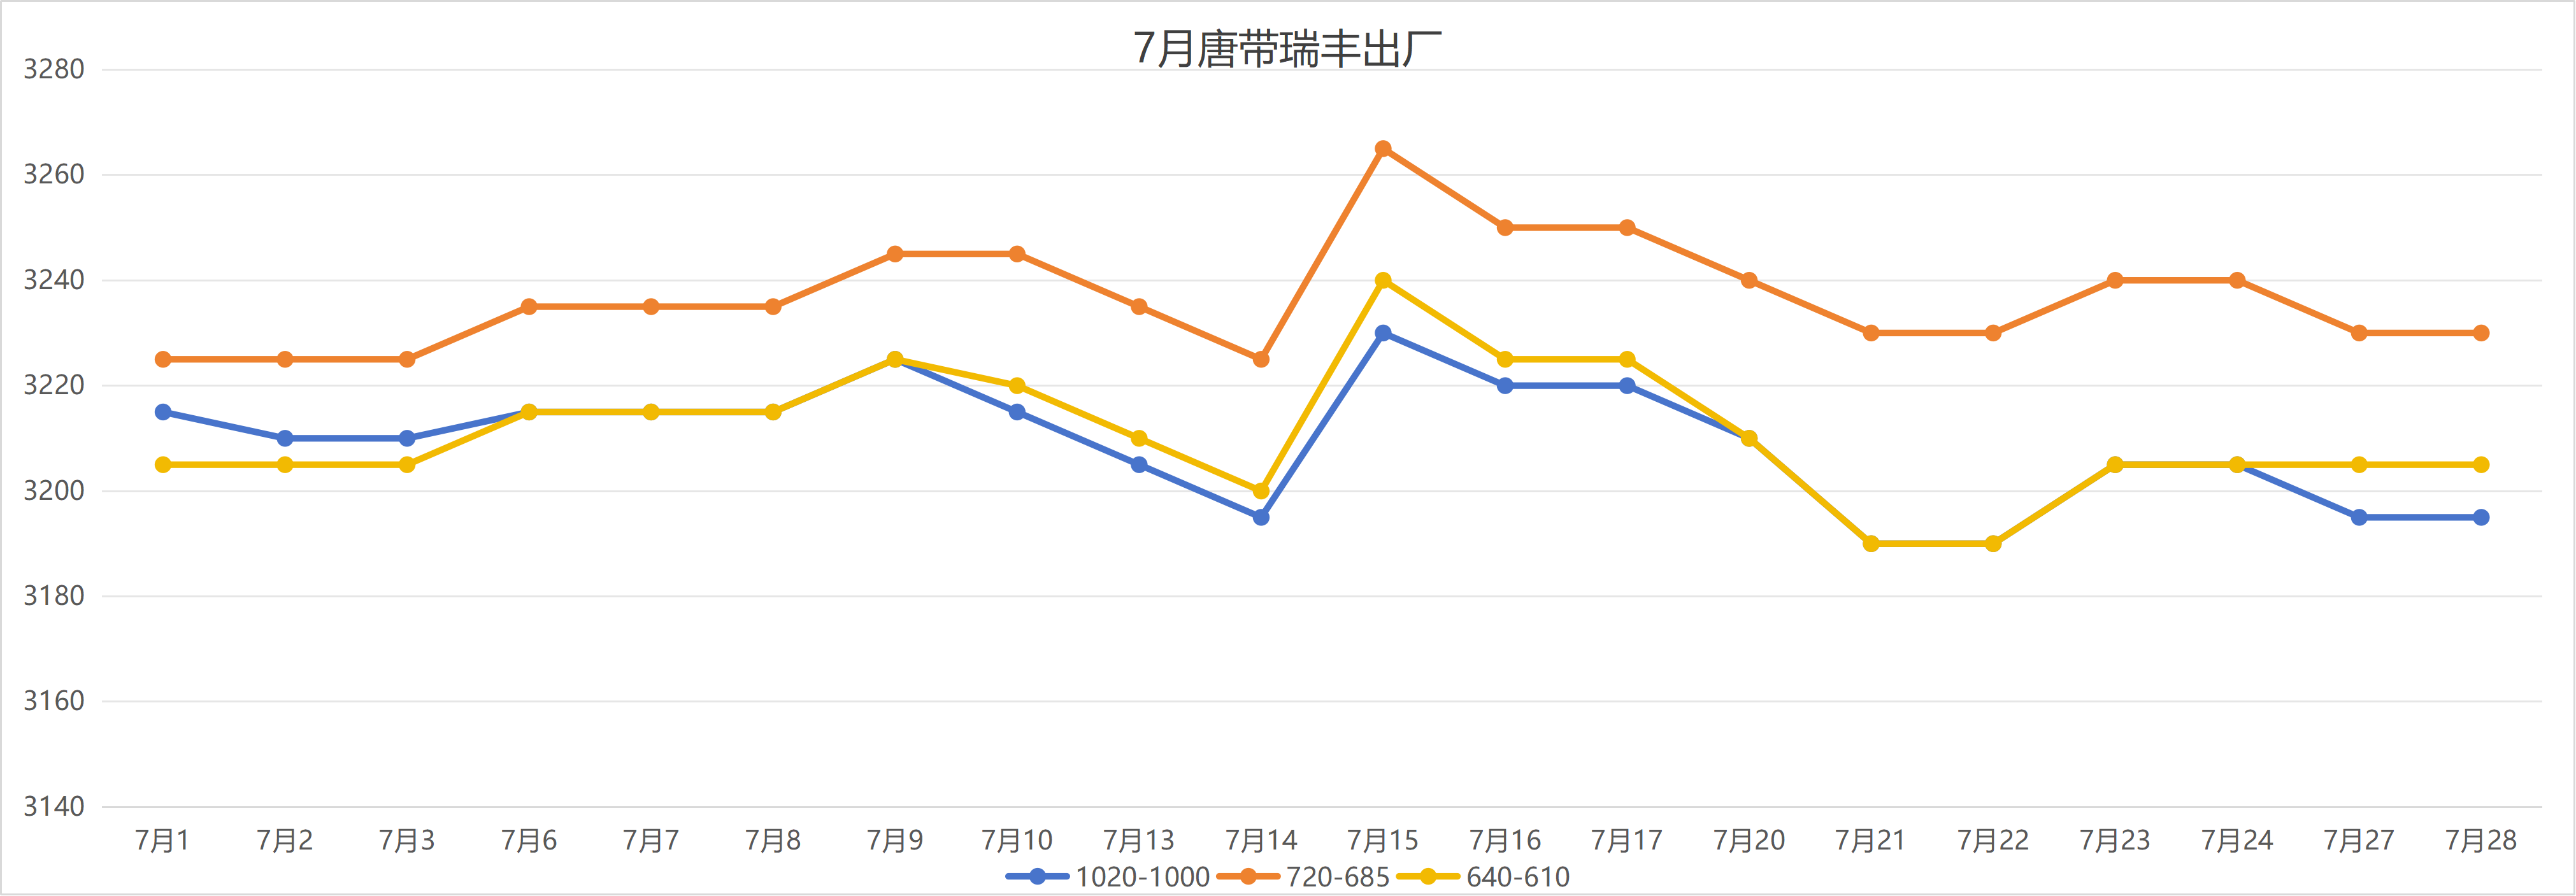
Steel price trends in July 2026
The July Steel Circulation PMI, jointly released by the China Metal Materials Circulation Association and Lange Steel, came in at 46.1%, up 0.3 percentage points from the previous month, recovering modestly from a low base but remaining in contraction territory. Among the sub-indices, 5 of the 10 categories that make up the Lange Steel Circulation PMI rose, while 5 declined. The indices for sales volume, total orders, delivery speed, inventory levels, and trend judgment posted gains, whereas the indices for selling prices, procurement costs, financing conditions, employment, and purchasing intentions fell.
Looking ahead to August, the steel market remains in the traditional off-season for demand, with overall trading expected to hover in a weak range-bound pattern, characterized by a divergence between stronger plate prices and weaker long-product prices. On the demand side, persistently high temperatures and heavy rainfall in early August continue to constrain outdoor civil construction, while the sluggish start of new real estate projects weighs on sentiment, keeping trading volumes for construction long steel weak. The transmission from infrastructure funding to actual physical work remains delayed, yet resilient orders from manufacturing sectors—such as machinery, shipbuilding, and new energy equipment—provide structural support for flat steel, reinforcing the divergence between long and flat products. As temperatures gradually moderate in late August, the drag from seasonal headwinds is expected to ease marginally, raising the prospect of a recovery in end-user procurement.
On the supply side, widespread industry losses are forcing steel mills to bring forward maintenance on blast furnaces and rolling lines, leading to a marginal contraction in steel output and temporarily easing supply pressure. This provides a floor for steel prices, though it is insufficient to reverse the overarching weak-demand dynamic that defines the off-season.
On the cost front, iron ore inventories at ports remain high, and steel mill production cuts are dampening demand for raw materials, keeping ore prices under pressure. Coking coal prices are fluctuating, while coke prices face multiple rounds of downward revision expectations. Overall, smelting costs are resilient but trending lower, with progressively weakening support from the raw materials side.
In summary, the August steel market is expected to maintain a balanced yet fragile equilibrium—characterized by weak demand, shrinking supply, and softening cost support—with prices continuing to fluctuate within a weak range. A modest recovery and rebound could emerge toward the latter half of the month, as seasonal constraints ease and supply-demand dynamics see marginal improvement. (Source: Lange Steel)